
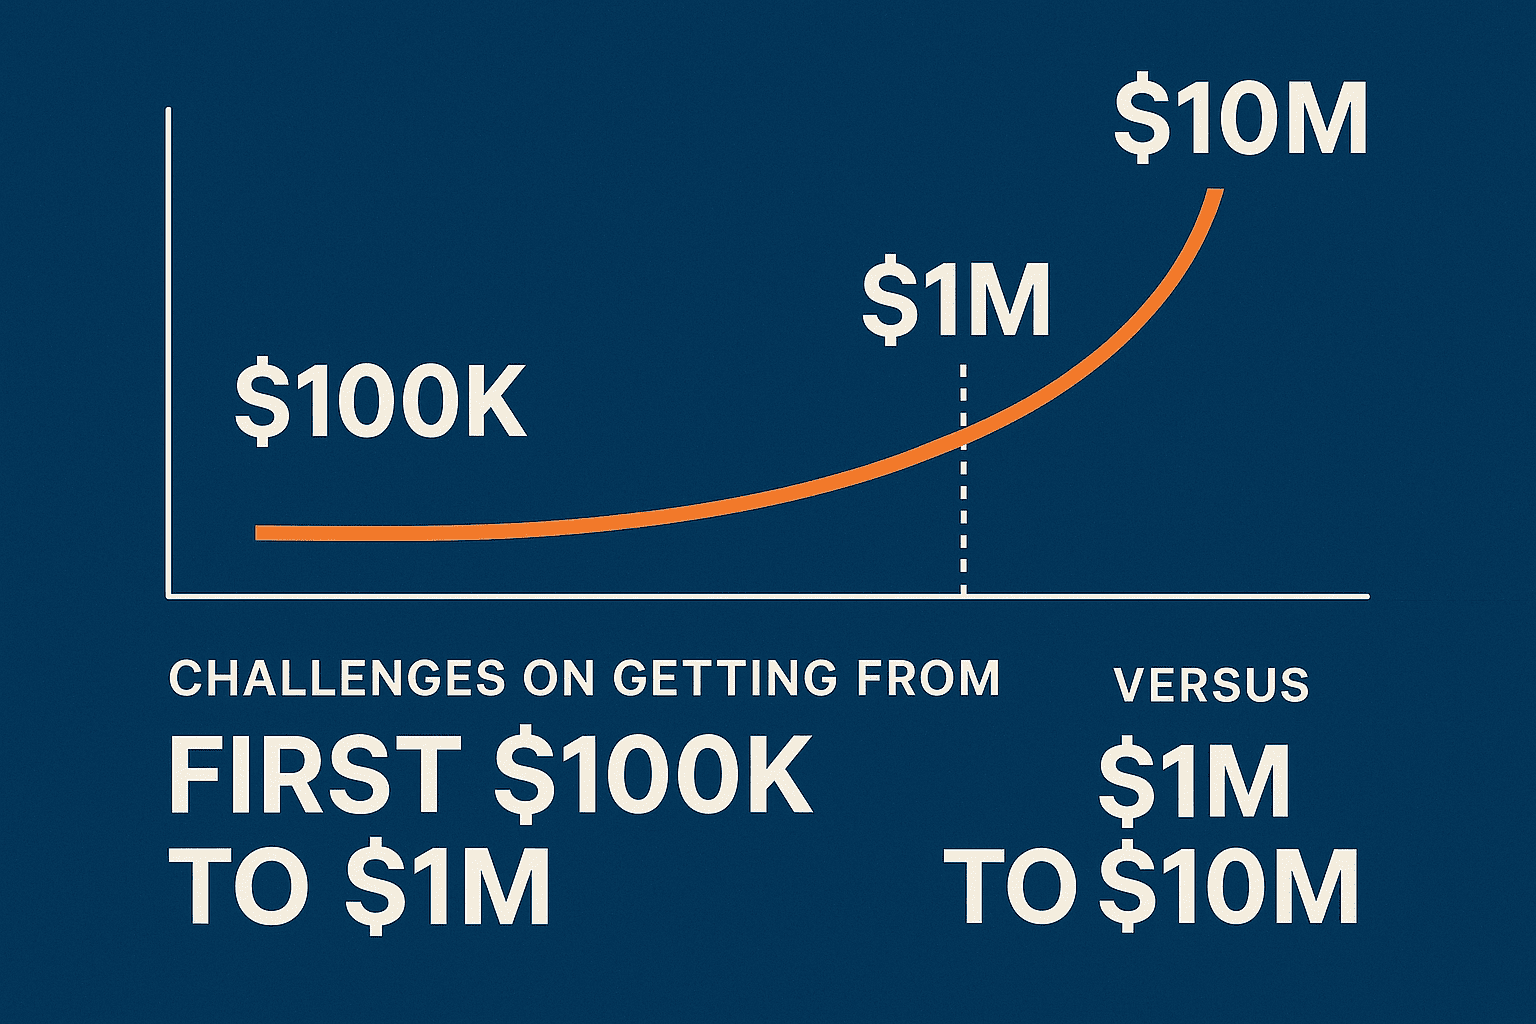
Getting your first $100,000 feels like climbing a mountain. Scaling that mountain all the way to $1 million is a completely different climb. And then scaling from $1 million to $10 million presents a whole new set of challenges.
In this post, I’m going to break down the distinct challenges of the two phases.
Building from $100K to $1M vs. $1M to $10M each requires its own mental models, tactics, and risk profiles. Understanding the differences will help you navigate the journey more effectively.
The Hardest Money to Make Is the First $100K
Before we get into the two primary phases, it is worth pointing out that all of the above pale in comparison to the challenge of making the first $100K. Charlie Munger once said, “The first $100,000 is a b***, but you gotta do it.” That’s because it requires creating something from nothing.
At this stage, you are still mostly living off active income (job, side hustles, small investments). The habits you form during this phase —saving and investing consistently, being disciplined, avoiding lifestyle inflation— set the stage for everything else.
The $100K to $1M Journey: The Grinding Phase
Progression from $100K to $1M is grinding. It is showing up and executing day after day, month after month. The money you make here is about compounding rather than leverage.
The key challenges are behavioral and personal rather than financial.
Saving vs. Investing
With $100K in the bank, every dollar counts. Deciding what to hold in cash/emergency fund vs. what to invest is a big challenge. You want to be aggressive, but not so aggressive you lose 40% of your net worth.
Balancing risk/reward when you have a limited cushion is tricky.
Market Volatility
At this stage, a 20–30% market crash is a traumatic experience. Your net worth is not yet diversified so the $30K disappearing from your $150K portfolio feels devastating. You have to keep reminding yourself $300K evaporating from a $2M portfolio would hurt a lot more.
Learning to emotionally stomach market drawdowns is essential.
Lifestyle Inflation
The biggest danger here is lifestyle inflation. As income starts to come in, the urge to spend is insatiable.
You can buy yourself a nice car. A bigger apartment. Luxury goods, travel, dining out. But every dollar spent on your present well-being is a dollar taken from your future millionaire self.
Learning to say no to lifestyle creep is one of the most valuable lessons of this phase.
Multiple Streams of Income
Another huge challenge: you can no longer make it to $1 million by working a 9–5 job and socking away the savings. The majority of people who achieve this by their 30s and 40s have multiple sources of income.
Side hustles. Business ventures. Aggressive stock and bond investments. Rental properties.
You still have to keep costs down, but also need to expand your income sources.
The $1M to $10M Journey: The Scaling Phase
Once you break $1M, money works differently. You are no longer struggling to save and invest; you have capital to work with. But new challenges come into play. Strategic rather than tactical.
Scaling vs. Saving
When you have $1M, saving another $20K a year feels meaningless. That’s why you have to shift your mindset from saving $1 a day to putting capital to work.
Buy a business. Real estate. Private equity. High growth stocks. But more importantly, you have to find creative ways to put that money into motion.
One can go from $100K to $1M with a high savings rate. But going from $1M to $10M requires scaling and leverage.
Risk Management
Another big shift: the types of risk you have to manage. At the $100K–$1M level, you risk blowing up your emergency fund. With $1M+, you are no longer worried about a couple of months of expenses.
You need to start thinking about asset allocation, risk concentration, inflation protection, tax losses, and economic downturns. Wealth preservation becomes an important skillset.
Systems, Not Hustles
You can no longer hustle your way to $10 million. Building to that level requires scaling. Systemic scaling.
- Businesses that don’t depend on you to run daily.
- Investments that grow in perpetuity without having to be touched.
- Teams and partnerships that amplify your impact.
Taxes and Wealth Structuring
This is where the complexity of “wealth management” really starts to kick in. Tax rates above 40% will eat up a huge chunk of your growth at the $1M+ level. Wealth protection, estate planning, sophisticated tax structures (trusts, LLCs, offshore accounts, tax-loss harvesting) become essential.
Without tax planning, your road from $1M to $10M will be much slower.
Psychological Challenges
The final challenge: complacency and a loss of hunger.
At the $100K–$1M level, you feel broke. You have that fire in the belly. The hunger that keeps you grinding. At $1M, people start thinking they are rich.
But to build to $10M, you need the same drive and focus and patience as when you had $100K.
Comparing the Two Stages Side by Side
| Stage | $100K → $1M | $1M → $10M |
|---|---|---|
| Mindset | Discipline, saving, compounding | Leverage, scaling, preservation |
| Key Challenge | Avoiding lifestyle creep, surviving volatility | Deploying capital efficiently, managing risk |
| Main Tools | High savings rate, index funds, side hustles | Businesses, real estate, private equity, tax planning |
| Risk Profile | Risk of not saving/investing enough | Risk of bad capital allocation, tax drag |
| Emotional Struggle | Patience while wealth grows slowly | Complacency and fear of losing wealth |
Summary
The $100K to $1M journey and the $1M to $10M journey are two very different beasts. They each require a unique set of skills, tools, and mental models.
$100K to $1M: Discipline, saving, surviving volatility, letting compounding do the heavy lifting.
$1M to $10M: Leverage, scaling, capital deployment, wealth preservation.
The skill sets required for each are totally different. One is about the hard work of discipline. The other is about the higher work of vision and strategy.
The journeys from $100K to $1M and from $1M to $10M are long ones. But having an understanding of the challenges of each stage will serve as a useful roadmap for your progress.
Keep learning: courses on this topic
Self-paced courses to put this article into practice.
 Udemy
Personal Finance from Zero: Budget, Save, Borrow & Invest
Money touches every day of your life, yet almost nobody is taught how it works. Where does your pay go between payday and the end of the…
View course
 Udemy
Invest Like a Pro: Your First Steps in Wealth Creation
A self-paced video course on budgeting, saving and investing and investing basics, with practical lessons you can apply right away.
View course
 Udemy
The Complete Personal Finance Course: Save, Budget & Invest
Take control of your money with a practical, step-by-step guide to personal finance, budgeting, saving, investing, debt management, and…
View course

Leave a Comment