
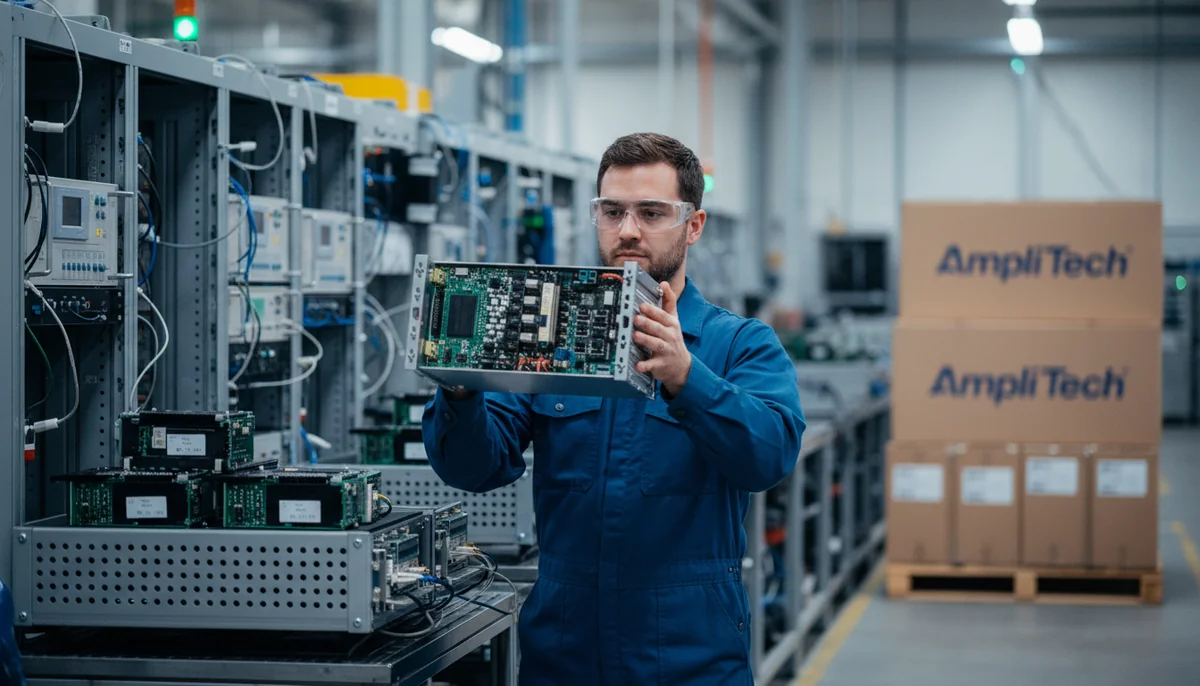
There is a particular type of investment opportunity that rarely announces itself loudly. It does not trend on financial news networks. It does not have a household name. But underneath the surface, all the right pieces are quietly locking into place — and those who spot it early tend to be rewarded most. AmpliTech Group Inc. (Nasdaq: AMPG) fits that description almost perfectly right now.
This is not a speculative story built on promises alone. It is a company with real revenue, real customers, real certifications, and a real pipeline — all converging at the same time. For investors researching AMPG stock, understanding what this company actually does, and why its current setup is unusual, is the starting point.
- What Is AmpliTech Group Inc. (AMPG)?
- The Revenue Story: From Early-Stage to Rapidly Scaling
- The 5G Open RAN Opportunity: Certified and Ready to Deploy
- The LOI Pipeline: Hundreds of Millions in Potential Revenue Just Getting Started
- Defense, Satellite, and Quantum: Three More Runways
- What Makes AMPG Structurally Differentiated
- The Re-Rating Thesis: When Does the Market Notice?
- Key Risks to Consider
- Final Thoughts: The Hidden Gem Thesis
Why these work:
The alt text is descriptive, front-loads the brand name, and uses natural language that matches how someone might search for images related to the company
The caption reinforces the editorial narrative (domestic manufacturing = competitive moat), adds the ticker for SEO context, and gives readers who skim images a reason to stop and engage
What Is AmpliTech Group Inc. (AMPG)?
AmpliTech Group, Inc. (NASDAQ: AMPG) is a manufacturing company in the communications equipment sector that focuses on advanced radio frequency (RF) and microwave technologies and 5G network solutions. According to company disclosures, AmpliTech designs, develops, engineers, manufactures, and distributes signal-processing components and systems used in satellite communications, telecommunications, space exploration, defense, quantum computing, and other communications networks.
The company was founded by Fawad Maqbool in 2002 and is headquartered in Hauppauge, NY. Over more than two decades, AmpliTech has carved out a niche that sits at the intersection of some of the most important technology themes of this decade: 5G/6G infrastructure, AI-driven wireless networks, quantum computing, satellite communications, and defense electronics.
What makes the business distinct is its focus on niche, high-frequency electronics where small design differences matter a lot. Customers choose suppliers like AmpliTech when standard parts are not enough and signal quality, size, and durability are critical. That puts the company in a specialized part of the electronics market where technical know-how is the main value it sells.
In short, AMPG makes the components that make modern communications work — the kind of components that aerospace giants, telecom carriers, and government agencies cannot simply source from a generic supplier.
The Revenue Story: From Early-Stage to Rapidly Scaling
One of the most important things to understand about AmpliTech in 2026 is the pace of revenue growth. This is not a company still searching for product-market fit. In 2025, AmpliTech Group’s revenue was $25.20 million, an increase of 164.99% compared to the previous year’s $9.51 million. Losses were -$7.01 million, -37.67% less than in 2024.
That is a 165% year-over-year revenue jump — and the losses are shrinking, not growing. Q1 2026 revenue jumped 48.6% year over year to $5.35M, while gross profit climbed 116% and gross margin expanded from 33% to 48%. Manufacturing and engineering revenue more than tripled, helping AMPG narrow its net loss despite ongoing growth spending.
Gross margin expanding from 33% to 48% in a single year is not a minor operational improvement. It reflects a company moving up the value chain — shipping more of its own proprietary, higher-margin hardware rather than distributing third-party components. That is a structural improvement in the business model, not a one-time event.
Cash, cash equivalents and marketable securities increased to approximately $18.4 million as of March 31, 2026. Working capital improved to approximately $25.4 million from $10.2 million on December 31, 2025. AmpliTech Group remains debt free.
A debt-free balance sheet with $18.4 million in cash and an improving current ratio gives management the runway to execute without diluting shareholders at unfavorable prices — a discipline the company has maintained through its growth phase.
The 5G Open RAN Opportunity: Certified and Ready to Deploy
The 5G infrastructure buildout is one of the defining investment themes of the 2020s. But within that broad trend, there is a specific architectural shift underway that creates particular advantages for a company like AmpliTech: the move toward Open RAN (O-RAN) networks.
Traditional 5G deployments are locked into proprietary hardware from a handful of dominant vendors — primarily Ericsson, Nokia, and Huawei. Open RAN breaks that proprietary lock by requiring standardized interfaces between hardware from different suppliers. This opens the market to specialist manufacturers like AmpliTech who can compete on performance and price rather than ecosystem lock-in.
AmpliTech announced its 64T64R Massive MIMO radio completed O-RAN ALLIANCE conformance certification (Certificate ID NANU26001). The radio supports 5G NR Band n78 (3.55–3.7 GHz) with up to 100 MHz carrier bandwidth. The certification verifies standards-based interoperability, aiding multi-vendor Open RAN deployments and phased network upgrades.
Even more significant is a milestone reached in May 2026. AmpliTech Group, Inc. (Nasdaq: AMPG) announced it has received full Federal Communications Commission (FCC) and Innovation, Science and Economic Development (ISED) Canada certifications for its complete 5G Native Distributed Antenna System (DAS) Solution. The approvals cover AmpliTech’s entire end-to-end hardware stack including the 5G Pico Radio, AC and DC Mother Hubs, and high-density Cascading Hubs. With both U.S. and Canadian certifications secured, AmpliTech is cleared for immediate commercial sale, shipment, and network integration across the North American market.
CEO Fawad Maqbool put the significance of this plainly: “We are no longer delivering standalone radios, we are bringing a fully compliant, end-to-end infrastructure solution to market. Our proprietary LNA integration provides this DAS with differentiated signal sensitivity and power efficiency. This dual-country certification gives our engineering, sales, and integration partners the ability to deploy full-scale networks immediately.”
That is a pivotal shift. AmpliTech is not just a component supplier anymore. It is an end-to-end 5G infrastructure provider with a certified, deployable product stack — cleared for immediate commercial rollout across the two largest North American telecommunications markets.
The LOI Pipeline: Hundreds of Millions in Potential Revenue Just Getting Started
One of the most discussed aspects of the AMPG investment thesis is the company’s letter of intent (LOI) pipeline. LOIs are non-binding commercial commitments, and it is important to view them with appropriate context. But their conversion trajectory for AmpliTech is instructive.
Production shipments have begun (over $20M under a $40M LOI); approximately $5M in funded purchase orders have been received toward a $78M LOI that the company says could grow past $100M; the company expects at least $50M revenue in FY2026.
AmpliTech has received a follow-on purchase order exceeding $1 Million as part of a $78M Letter of Intent (LOI) from a Strategic Open RAN Systems Integrator. The company is also progressing with deliveries on $10M+ orders from another major 5G industry player, with shipments that began in April 2025. AmpliTech has achieved CE/REACH and FCC certifications for global deployment and confirms all funded orders from both LOIs are on track for fulfillment within the current fiscal year.
LOIs are not revenue. But LOIs that are converting into funded purchase orders, with shipments already underway, are a different thing entirely. The pattern here — LOIs signed, certifications achieved, funded orders following — suggests that AMPG’s commercial relationships are maturing in the right direction.
Defense, Satellite, and Quantum: Three More Runways
The 5G story gets most of the attention in recent AMPG coverage, but it is only one of several growth vectors the company is pursuing simultaneously.
Amplitech is widely recognized as an industry leader and has developed and supplied solutions to Fortune 500 companies, and Military and Government agencies including Lockheed Martin, NASA, Boeing, Raytheon, and the Israeli Government. These are not cold-call relationships. They represent years of technical validation by some of the most demanding customers on earth.
The defense electronics market is undergoing its own structural expansion, driven by increasing global defence budgets, the proliferation of satellite communications, and the modernisation of military infrastructure. AmpliTech continued to advance commercialization initiatives related to satellite and defense communications applications and next-generation wireless infrastructure solutions.
On the quantum computing side, AmpliTech’s cryogenic amplifiers — components that operate at extremely low temperatures — are positioned for a market that is still in its early commercial innings but is attracting enormous investment from governments and private technology companies alike. The physics of quantum computing requires the same fundamental expertise in signal amplification that AmpliTech has been building for more than two decades. This is not a pivot — it is a natural extension of existing core competency.
AmpliTech’s O-RAN CAT B 64T64R Massive MIMO radio powered Northeastern University’s first open-source Massive MIMO AI-RAN prototype. The convergence of AI and radio access networks — referred to as AI-RAN — is an emerging frontier that major carriers are investing in heavily. AmpliTech’s hardware is already being used in cutting-edge research at tier-one institutions, which is a meaningful form of technical validation.
What Makes AMPG Structurally Differentiated
It is easy to find small-cap companies operating in exciting sectors. It is harder to find ones that check multiple structural differentiation boxes simultaneously. AmpliTech checks several that matter:
1. Fully Integrated Domestic Manufacturing At a time when supply chain resilience and domestic manufacturing have become geopolitical priorities — particularly for defense and critical communications infrastructure — AmpliTech’s U.S.-based, vertically integrated production is a genuine competitive advantage. It is also a qualification requirement for many government and defense contracts.
2. Founder-Led, Aligned Management Fawad Maqbool founded the company in 2002 and continues to serve as both CEO and CTO. Founder-led companies with technical CEOs who retain meaningful ownership tend to make decisions with a longer time horizon than professional managers. His continued open-market share purchases signal conviction, not just contractual obligation.
3. Debt-Free Balance Sheet With Multi-Year Runway The company finished Q1 2026 with $18.4M in cash, stronger working capital, and no debt, giving AMPG room to execute. For a micro-cap company navigating the expensive transition from R&D to commercial scale, this financial positioning reduces the execution risk materially.
4. Multiple Certifications Removing Regulatory Risk The recent FCC, ISED Canada, and O-RAN Alliance certifications are not incremental achievements. They are the regulatory prerequisites that convert a promising product into a shippable, deployable commercial solution. With certifications now secured across its core product lines, AMPG has removed a meaningful category of uncertainty from its investment thesis.
5. Revenue Acceleration, Not Just Growth Revenue is forecast to grow 49% per annum, and the company is expected to make a profit of US$3.20m in 2026. Moving from losses to profitability while growing revenue at this pace is the kind of inflection that historically triggers significant re-rating of small-cap valuations.
The Re-Rating Thesis: When Does the Market Notice?
The core argument for AMPG at current levels is not complicated. Every major revenue catalyst is in its earliest innings — simultaneously.
The 5G Native DAS product received its full FCC and ISED Canada certifications in May 2026. Commercial deployments are only just beginning. The $40M LOI has production shipments underway; the $78M LOI has initial funded orders flowing. The O-RAN Alliance certification was completed in January 2026. Defense and satellite programs with Lockheed Martin, Boeing, Raytheon, and NASA represent relationships that are expanding, not static. And the quantum computing opportunity has not yet been meaningfully priced into any analyst model.
The full FCC and ISED Canada certifications for the 5G Native DAS look most relevant for investors, because they move a complete, already-ordered indoor 5G product stack from engineering into shippable, revenue-generating territory. That matters for the thesis that upfront qualification and activation costs will give way to more scalable deployments, potentially helping AmpliTech work toward the higher, more stable margins implied in its longer-term 5G, satellite, and quantum ambitions.
Small-cap stocks tend to re-rate when revenue inflects, when regulatory milestones are achieved, and when institutional investors begin to take notice. AmpliTech has hit all three of these conditions in 2025 and 2026 — and the company’s market capitalization still does not reflect the scale of the opportunity in front of it.
Key Risks to Consider
A balanced assessment of any investment requires an honest look at risks. For AMPG, the most notable are:
- Customer concentration. A significant portion of current revenue is tied to a small number of large carriers and defence contractors. Delays, cancellations, or renegotiations by any one customer would have an outsized impact on near-term results.
- LOI-to-revenue conversion. LOIs are non-binding. The pipeline is large, but until funded purchase orders are in hand and shipments are confirmed, the revenue is not guaranteed.
- Execution risk at scale. Transitioning from a small-run, custom-component manufacturer to a high-volume infrastructure supplier requires operational infrastructure that takes time to build.
- Continued losses. While losses are shrinking, the company is not yet profitable on a GAAP basis. Profitability projected in 2026 depends on revenue growth maintaining its trajectory.
These are real risks. They are also the reason the stock trades at the valuation it does — and why the upside is as significant as it appears if execution continues.
Final Thoughts: The Hidden Gem Thesis
AmpliTech Group (AMPG) is one of those rare sub-$400 million companies where the investment thesis is not dependent on a single catalyst. It is dependent on four simultaneous catalysts — 5G Open RAN commercialization, defense program expansion, carrier LOI conversion, and quantum computing readiness — all of which are moving forward at the same time, from a position of financial strength.
The stock has moved. But the re-rating that typically accompanies sustained revenue growth and margin expansion has not fully arrived. The company reaffirmed FY2026 revenue guidance of at least $50M and advanced a large 5G LOI pipeline. If that guidance is hit, the current market capitalization will look deeply misaligned with the fundamental reality of the business.
Those who do the work to understand what AMPG actually does — and why its combination of U.S. manufacturing, technical depth, blue-chip customer relationships, and certified product pipeline is genuinely rare — may be looking at an opportunity that the broader market has not yet fully priced in.
This article is for informational and educational purposes only. It does not constitute financial advice. Always conduct your own due diligence and consult a licensed financial advisor before making investment decisions. Past performance is not indicative of future results.
Keep learning: courses on this topic
Self-paced courses to put this article into practice.
 Udemy
How to Invest in Stocks, Mutual Funds & ETFs for Beginners
Are you ready to take charge of your own investment accounts? Make informed decisions about how to manage your money and let it work for…
View course
 Udemy
How To Confidently Invest & Analyze Stocks Like an Expert
Are you tired of feeling overwhelmed by the stock market or unsure if a stock is actually a good investment? This course, "Investing in…
View course
 Udemy
How To Invest In Stocks In 15 Minutes?
This is for anyone who wants a quick lesson on stocks and want to start trading stocks today—Within 15 minutes. This beginner guide will…
View course
Leave a Comment